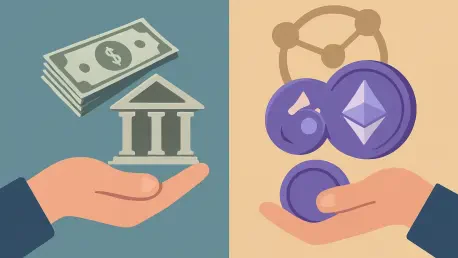
The distinction between crypto exchanges and digital banks is blurring as these entities compete for the same pool of global capital and retail deposits. For generations, the foundational agreement of retail banking has remained largely unchallenged: customers provide their hard-earned capital for safekeeping, and in return, banks utilize that liquidity to fuel a vast array of lending and investment activities. While this model historically provided stability, the interest returned to the average depositor has dwindled to near-negligible levels, often failing to keep pace with inflation or the true value of the underlying assets. As we navigate the current landscape, decentralized finance protocols are emerging as a direct threat to this status quo by offering transparent, program-driven alternatives that prioritize depositor returns. This shift is not merely a technical upgrade but a fundamental reimagining of what it means to hold a balance, moving away from passive storage toward active, high-velocity capital utilization across global markets.
The Modern Yield Disparity: Banks Versus Protocols
Industry leaders are increasingly vocal about the structural inequities found in traditional savings accounts, with some characterizing the current banking model as an outdated mechanism that disproportionately benefits institutions over individuals. The primary point of contention is the massive spread between the low interest paid to savers and the high rates banks earn on the same funds through mortgages and commercial loans. In contrast, the on-chain economy provides a more direct relationship between supply and demand, allowing users to capture yields that reflect actual market conditions. For example, platforms like Coinbase have successfully integrated stablecoin-based opportunities that offer 3.75 percent on USDC, while specialized lending products linked to Morpho provide returns as high as 7 percent. These figures are not just incremental improvements; they represent a significant departure from the fractional percentages offered by legacy banks, forcing a migration of retail wealth toward more efficient decentralized platforms.
To accelerate this transition, the industry has embraced a hybrid operational philosophy known as the “DeFi mullet,” which prioritizes a familiar user experience while leveraging decentralized back-end rails. This approach ensures that the complexity of blockchain interactions is hidden behind intuitive interfaces, making high-yield opportunities accessible to individuals who may not have deep technical expertise. Beyond ease of use, this model introduces a level of transparency that traditional financial institutions have historically resisted. While a standard bank often functions as a “black box” regarding the specific allocation of customer deposits, decentralized protocols like Maple provide granular, real-time data on fund distribution. By publishing allocation updates as frequently as every hour, these platforms allow participants to verify exactly where their capital is deployed and how it is being collateralized. This radical visibility builds a layer of trust that is fundamentally different from the institutional reliance characteristic of the previous era.
Autonomous Agents: The Next Catalyst for Adoption
The next phase of this financial evolution is being driven by the integration of autonomous AI agents designed to manage wealth with a level of precision and speed that far exceeds human capabilities. These digital entities are capable of scanning the entire global market in milliseconds to identify the most lucrative yield-generating opportunities while balancing them against specific risk profiles. However, a significant barrier remains the closed nature of traditional banking systems, which often function as walled gardens with restricted access for automated software. Most legacy banks do not offer the robust, permissionless APIs required for an AI agent to move funds seamlessly across different platforms or institutions. This limitation creates a massive advantage for blockchain-native environments, which are programmable and open by design. As a result, capital is increasingly flowing into protocols where software agents can operate without friction, turning what used to be static savings into a dynamic, 24/7 optimized portfolio.
Safety remains a paramount concern as these autonomous systems take control of larger portions of the global liquidity pool, leading to the development of sophisticated safeguard models. Protocols like Morpho are at the forefront of this movement, designing layered security frameworks specifically tailored for AI-driven transactions. These systems typically involve a multi-stage process where proposed moves are first simulated to predict potential outcomes and identify any hidden anomalies before they occur. Furthermore, final execution remains tied to specific cryptographic signatures, ensuring that the ultimate control of the assets stays with the holder rather than the software alone. Institutions and high-net-worth individuals are also utilizing programmable controls that set strict daily limits and allowlists for approved smart contracts. This combination of high-speed automation and rigorous technical boundaries provides a middle ground where efficiency does not come at the expense of security, making decentralized systems the natural home for the next generation.
Navigating the Trade-Offs: Risk and Future Steps
While the rewards of decentralized finance are compelling, participants must weigh them against the technical and economic risks that define the on-chain environment. Technical risk remains a primary concern because all operations are dictated by smart contracts, which are essentially self-executing code stored on the blockchain. Unlike the traditional system where a bank can reverse a mistake, code-based errors or exploits in DeFi are often final and irreversible. Furthermore, the economic model of over-collateralization provides a safety net, yet it is not entirely immune to extreme market volatility. If the value of underlying assets drops too sharply, the liquidation process might fail to keep pace, potentially impacting the returns of liquidity providers. Additionally, the lack of government-backed insurance means that liquidity is entirely dependent on the depth of the protocol’s pools. Understanding these structural trade-offs is vital for anyone seeking to move away from the perceived safety of FDIC-insured deposits.
The transition toward decentralized protocols functions as a pivotal moment in the history of capital management, as it successfully challenges the century-old dominance of traditional banking. Investors who adjust their strategies early are able to capture significant yields while legacy institutions scramble to update their technological infrastructure. This era of transformation highlights the necessity of technical literacy, as the ability to evaluate smart contract security becomes just as important as understanding interest rates. Organizations that integrate on-chain back ends realize immediate gains in efficiency and transparency, setting a new standard for the global financial ecosystem. As autonomous agents begin to manage the majority of retail liquidity, the concept of a static bank account becomes obsolete. Those who move their idle deposits into these programmable environments participate in a more dynamic market where assets are never truly dormant. This shift prepares the foundation for a future where individual control over capital is absolute.