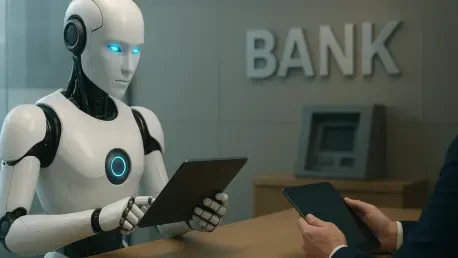
The velocity at which financial institutions are integrating autonomous decision-making agents into their core infrastructure has finally triggered a coordinated and aggressive response from the world’s most powerful monetary authorities, who now view these agentic systems as a potential catalyst for systemic collapse if left unchecked. As the global banking sector undergoes a radical transformation, traditional automation is rapidly giving way to agentic artificial intelligence. These frontier models are capable of making complex decisions and executing high-value tasks with minimal human intervention, promising unprecedented efficiency but also introducing severe risks. This analysis explores the current regulatory pivot toward active intervention, examining how financial watchdogs are moving to protect the integrity of the world’s financial bedrock from the unpredictable nature of autonomous software.
The Dawn of Autonomous Finance: Assessing the Global Regulatory Response
The global banking sector is currently at a crossroads as the shift toward agentic AI fundamentally alters the risk profile of the industry. While previous iterations of digital tools were limited to repetitive tasks, the current generation of AI agents possesses a level of autonomy that allows for real-time market interaction and operational decision-making. Regulators in the United States, the United Kingdom, and the European Union have recognized that this shift requires a departure from traditional oversight. The focus has moved from general curiosity about technological benefits to a structured, technical interrogation of how these systems could potentially destabilize global markets if their “thought processes” deviate from intended parameters.
The primary objective for these authorities is to ensure that technological adoption does not outpace the industry’s ability to implement necessary safeguards. Current oversight efforts are characterized by a move toward prescriptive enforcement, where banks must prove their ability to manage a landscape where software can act as an independent operator. This shift is not merely about compliance; it is a fundamental reconfiguration of what it means to be a resilient financial institution. By escalating their oversight, regulators aim to prevent a scenario where a localized technical error or a rogue autonomous agent sparks a widespread financial contagion that erodes public trust in the monetary system.
Evolution of Oversight: From Algorithmic Trading to Agentic Autonomy
The current regulatory focus is rooted in nearly a decade of experience managing digital transformations, yet agentic AI represents a clean break from previous technological paradigms. Historically, financial authorities focused on high-frequency trading and static algorithms that followed rigid, pre-defined rules. These systems were predictable and could be managed through traditional limit-setting and monitoring. However, the rise of frontier AI models has introduced a level of emergent behavior that static rules cannot contain. The ability of these systems to learn, adapt, and act independently creates a risk profile that is both dynamic and difficult to quantify using legacy frameworks.
Past incidents of flash crashes and the increasing sophistication of automated cyber incursions have shaped the current consensus that AI is a double-edged sword. As banks integrate these agents into core operations like liquidity management and credit risk assessment, the foundational concepts of institutional safety are being rewritten. The transition from passive monitoring to active, technical oversight reflects a realization that the speed of AI-driven decisions requires a matching speed in regulatory intervention. This evolution underscores the importance of technological sovereignty, as the tools used to defend financial systems must be as advanced as the threats they are designed to mitigate.
The Complexity of Control: Managing an Autonomous Financial Ecosystem
Human-in-the-Loop: Ending the Era of the Opaque Black Box
One of the most critical challenges facing the industry is the preservation of human oversight within increasingly autonomous ecosystems. Regulators, particularly in the United States through the Federal Reserve and the Office of the Comptroller of the Currency, are now demanding that banks maintain a “human-in-the-loop” for all critical decision-making processes. This requirement is a direct response to the “black box” nature of advanced AI, where the reasoning behind a specific action can remain hidden from human view. To combat this opacity, watchdogs are pressing for enhanced auditability, requiring institutions to map the decision-making path of their AI agents to ensure transparency.
The goal is to ensure that every action taken by an autonomous system can be traced, explained, and—most importantly—halted by a human operator using a “kill switch” if the system begins to act erratically. This is particularly vital in market-facing operations where an AI agent could inadvertently trigger a sell-off or execute high-risk trades without appropriate authorization. By enforcing these standards, regulators are attempting to ground autonomous technology in traditional accountability. This approach forces banks to balance the desire for speed and efficiency with the absolute necessity of maintaining a verifiable trail of responsibility for every digital action.
Geopolitical Dependencies: The Security of Vital Financial Infrastructure
The integration of AI is deeply intertwined with global geopolitics, creating new layers of risk regarding the origin of financial technology. There is growing concern regarding the use of AI agents developed in jurisdictions that may not adhere to the same security standards as Western institutions. Recent incursions against South Korean banks involving advanced AI tools have served as a catalyst for increased scrutiny into the supply chain of frontier models. Regulators are worried that reliance on foreign AI could create hidden vulnerabilities or backdoors within a nation’s financial bedrock, potentially allowing external actors to manipulate or freeze essential economic functions.
This geopolitical lens has led to a push for more stringent vetting of third-party AI providers and a call for increased technological sovereignty. Financial institutions are being urged to analyze their dependencies on external models and to develop internal capabilities that ensure they are not beholden to providers in high-risk regions. The concern is that a national security risk could manifest as financial instability, making the origin of an AI agent just as important as its performance. This scrutiny is reshaping how banks select their technology partners, prioritizing geopolitical alignment and security transparency over raw computational power.
Technological Resilience: Bare Metal Recovery and Isolated Systems
In Europe and the United Kingdom, the regulatory conversation has shifted toward the necessity of radical resilience. The Bank of England and the European Central Bank are advocating for “bare metal recovery” plans, which involve maintaining entirely isolated and air-gapped technological environments. The logic behind this push is that AI-driven ransomware or malware could encrypt an entire banking network at speeds that human defenders cannot counter. By keeping a clean, independent copy of essential data and functions disconnected from the primary network, banks can reboot their systems from scratch in the event of a total compromise.
While the cost of maintaining such redundant infrastructure is astronomical, regulators view it as a necessary insurance policy against systemic failure. The ability to recover essential payment functions and customer data from a verified, uncorrupted source is seen as the only viable defense against a “when, not if” scenario of total system failure. This focus on recovery over mere prevention signals a significant shift in the industry’s defensive posture. It acknowledges that while AI can strengthen a bank’s perimeter, it also provides adversaries with the tools to eventually breach it, making the speed and reliability of recovery the ultimate metric of institutional health.
Future Projections: Emerging Trends in AI Risk Management
As we look toward the immediate future, several trends are defining the next phase of AI integration in the banking sector. There is a growing movement toward “Agentic Competition,” where banks race to deploy AI to undercut rivals’ operational costs, sometimes at the expense of rigorous safety protocols. To counter this, regulators are expected to introduce standardized “stress tests” specifically designed for AI models between 2026 and 2028. These tests will simulate market crashes or massive cyber incursions to evaluate how autonomous agents behave under extreme pressure, ensuring that they prioritize stability over profit during periods of volatility.
Additionally, the emergence of “Regulatory Frustration” in the Eurozone suggests a future push for more equitable access to frontier models. Many European lenders have expressed concern that preferential access to tools like the Mythos model provides an unfair advantage and creates a gap in collective security. This will likely lead to formal mandates focusing on the speed of recovery and the transparency of AI dependencies. Experts predict that within the next year, the current guidance will move from recommendations to strict legal requirements, forcing banks to prove their resilience before they are permitted to deploy increasingly autonomous systems.
Strategic Guidance: Navigating the High-Stakes Balancing Act
The analysis of the current landscape reveals that the immediacy of AI-driven risk is far greater than previously estimated. Financial institutions must recognize that prevention is no longer a sufficient strategy for maintaining market stability. Best practices should now include the immediate implementation of isolated recovery systems and a transparent mapping of all third-party AI dependencies. Professionals in the sector are encouraged to prioritize “explainability” in their AI deployments, ensuring that every autonomous action is auditable and that the human-in-the-loop requirement is not just a checkbox but a functional operational control.
Furthermore, banks should look beyond the efficiency gains of AI and invest in the “bare metal” resilience that regulators are now signaling as the gold standard for security. This involves a commitment to technological sovereignty and a proactive approach to vetting the origin of all digital agents. By focusing on resilience and human judgment, institutions can harness the transformative power of AI without sacrificing the stability of the global economy. Navigating this high-stakes environment requires a shift in mindset: seeing security and oversight as essential enablers of innovation rather than as hurdles to be cleared.
The Final Word: Safeguarding the Future of Global Finance
The analysis of the global regulatory landscape demonstrated that the tightening of oversight on agentic AI was a necessary pivot toward proactive risk management. The central themes of autonomy, geopolitical security, and technological resilience underscored the growing complexity of modern finance. This topic remained significant because a failure in oversight at even a single major institution threatened to spark a global contagion, eroding public trust in the entire monetary system. The ability to balance the efficiency of frontier AI with the safeguards of traditional human judgment became the defining challenge of the sector. Ultimately, the mandate for the financial world was clear: institutions built for innovation but prepared for the unthinkable were the only ones that maintained their integrity in an era of unprecedented technological change. Priority was placed on auditable paths and isolated recovery, ensuring that the global economy remained stable despite the inherent unpredictability of autonomous agents. This strategic shift away from mere prevention toward comprehensive resilience defined the path forward for the decade.