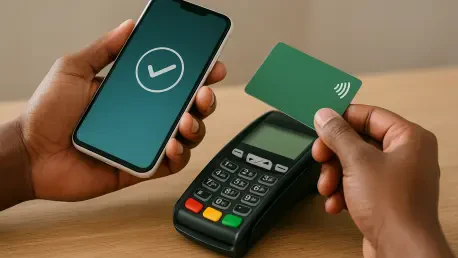
Small business owners and rural dwellers often find themselves marginalized by digital payment systems that fail to account for unreliable internet connectivity and limited electricity. While the African continent is witnessing an unprecedented surge in digital transformation, the actual implementation of Instant Payment Systems (IPS) has revealed a significant disconnect between technological availability and practical usage. As of the current period, approximately 75 percent of African adults own a mobile phone, and nearly 58 percent have access to a bank or mobile money account. However, these figures mask a deeper reality where nearly half of the adult population remains completely sidelined from the digital financial ecosystem. This “usage gap” highlights the fact that simply providing hardware or a basic account is insufficient for true economic participation. To bridge this divide, payment systems must evolve into infrastructures that are not only high-speed but also affordable and resilient enough to function in environments with minimal resources. The promise of digital connectivity depends on creating a landscape where transactions are processed instantly regardless of the user’s geographic location or the sophistication of their mobile device.
System Architectures: Moving From Bilateral to Multilateral Models
The structural design of a payment network often dictates its efficiency and the ultimate cost to the end user. Currently, a significant portion of the African financial landscape is hampered by bilateral payment arrangements. In such a setup, every financial institution, whether it is a traditional bank or a mobile money operator, must establish an individual technical agreement and a unique connection with every other provider in the network. This decentralized approach is inherently inefficient because it creates a complex “mesh” of connections that is difficult to manage and expensive to maintain. As these institutions grapple with the high operational costs of maintaining hundreds of individual links, the financial burden is inevitably passed down to the consumer in the form of higher transaction fees. For a street vendor or a small-scale farmer, these costs often make digital payments less attractive than traditional cash transactions, further entrenching the informal economy and slowing the pace of modernization.
In contrast, the transition toward a multilateral system represents the gold standard for achieving comprehensive financial inclusion across the continent. A multilateral arrangement functions as a unified “one-to-many” infrastructure, allowing a single institution to connect to a central hub and immediately gain the ability to interact with every other participant in the ecosystem. This model significantly reduces the friction involved in moving money between different providers, such as transferring funds from a fintech wallet to a traditional microfinance bank account. By simplifying the technical requirements for interoperability, multilateral systems lower the barrier to entry for smaller financial players, which in turn fosters competition and drives down prices for consumers. This architectural shift is essential for building a robust digital economy where the movement of value is as seamless as the exchange of information, ensuring that even those in the most underserved sectors can participate in the formal financial market without being penalized by high fees.
Measuring Success: The Nigerian Strategic Blueprint
To accurately assess the progress of digital payments, industry experts utilize a maturity framework that classifies systems into three distinct categories: basic, progressed, and mature. A basic system typically supports fundamental peer-to-peer transfers and simple merchant payments but often lacks the broad interoperability needed for a truly integrated economy. As systems evolve into the progressed stage, they begin to incorporate more complex use cases and better governance structures. However, achieving a mature status requires more than just high-speed technology; it necessitates a comprehensive approach that includes robust consumer protection, clear redress mechanisms, and a business model that ensures long-term affordability. Of the 36 domestic and regional systems currently operating across Africa, the vast majority still fall into the basic or progressed categories, indicating that there is still significant work to be done in refining the regulatory and operational foundations of these networks.
Nigeria’s NIBSS Instant Payment (NIP) system currently stands as the primary example of a mature-level system on the continent. Managed by the Nigeria Inter-Bank Settlement System, NIP facilitates instant transfers across a diverse range of financial institutions, from large commercial banks to smaller fintech startups. The success of the Nigerian model is rooted in its focus on the user experience and its institutionalized approach to resolving complaints. By ensuring that consumers have a reliable way to address failed transactions or fraudulent activity, the system has built a high level of public trust, which is a prerequisite for widespread adoption. This maturity demonstrates that technological speed must be balanced with a governance structure that prioritizes the rights of the sender and the recipient. Other nations looking to replicate this success must look beyond the initial deployment of software and invest in the regulatory frameworks that protect the economic interests of their citizens.
Economic Barriers: Overcoming Cross-Border Friction and Regulation
While domestic payment systems are maturing, the process of moving money across African borders remains one of the most significant pain points for regional integration. The fragmentation of currencies and regulations across 55 member states creates a massive amount of friction that slows down trade and drains resources. It is estimated that approximately $5 billion is lost annually due to currency conversion costs, particularly because many transactions are still routed through intermediary currencies like the U.S. dollar rather than being settled directly between African central banks. For small and medium-sized enterprises (SMEs), these high costs and the delays associated with cross-border transfers represent a direct barrier to expansion. If transaction fees were reduced to a target of three percent, an estimated $1 billion could be returned to African families and businesses each year, providing a substantial boost to the continent’s internal trade and overall economic resilience.
Addressing these economic hurdles requires more than just technical fixes; it demands a concerted effort toward regulatory harmonization. Currently, the lack of common rules across 40 different central banks acts as a primary obstacle to the success of the African Continental Free Trade Area. Since the beginning of 2026, there has been a renewed focus on creating a unified framework that covers essential areas such as licensing, anti-money laundering protocols, and data governance. Such a framework would allow financial service providers to “passport” their services across borders more easily, reducing the need for redundant compliance processes in every new market. By establishing uniform standards for consumer protection and supervisory cooperation, African nations can create a more predictable and secure environment for investors and users alike. This regulatory alignment is the “digital plumbing” necessary to ensure that capital can flow freely across the continent, supporting a more integrated and prosperous regional economy.
Trust and Security: Mitigating the Risks of Accelerated Transactions
The very speed that makes instant payments so convenient for legitimate users also makes them an attractive target for sophisticated criminal networks. Because funds are transferred in a matter of seconds, fraudsters can often move or withdraw stolen money before the victim even realizes that a crime has been committed. This has led to an increase in “authorized push payment” scams, where individuals are manipulated through social engineering or impersonation into willingly sending money to a criminal. The psychological impact of these crimes can be devastating, particularly for vulnerable users who are new to digital finance and may not have the tools to verify the identity of a recipient. If left unaddressed, this rising tide of fraud threatens to undermine public confidence in digital systems, potentially driving users back to the perceived safety of physical cash and stalling the progress of financial inclusion.
To maintain the integrity of the digital ecosystem, payment systems must implement advanced security features that operate in real time without sacrificing the speed of the transaction. This includes the deployment of recipient verification tools, which allow a sender to see the legal name of the person or business they are paying before they confirm the transfer. Additionally, financial institutions must adopt clearer reimbursement protocols so that victims of fraud are not left to bear the total cost of a security breach alone. Building trust also requires a commitment to transparency, where users are clearly informed about how their data is used and what steps they can take if a transaction goes wrong. By prioritizing the safety and security of every participant, regulators and providers can ensure that the move toward instant payments does not inadvertently create a new set of risks for the very people the technology is intended to help.
Human-Centric Reporting: Leveraging Media for Public Accountability
The ultimate success of inclusive payment systems depends on how they are perceived and navigated by the general public, a process where the media plays a pivotal role. Journalists and storytellers serve as the essential bridge between the technical jargon of central banks and the lived experiences of citizens in rural or underserved areas. By looking beyond official corporate announcements and reporting on the “last mile” of financial delivery, the media can highlight where systems are failing—such as chronic network downtime in remote villages or hidden transaction fees that disproportionately affect low-income users. This human-centric approach to reporting shifts the narrative from abstract technological milestones to the real-world impact on families and small businesses. When the media holds policymakers accountable for the accessibility and reliability of these services, it ensures that the push for digital transformation remains focused on the needs of the people.
The journey toward total financial inclusion required a fundamental shift from simple technological deployment to a more sophisticated, human-centered design philosophy. Success was ultimately measured by the ability of the most remote users to trust the systems they interacted with on a daily basis. Stakeholders recognized that regulatory friction was the primary bottleneck and moved toward a centralized licensing model that allowed fintechs to scale across borders without facing redundant hurdles. By prioritizing consumer protection protocols and real-time fraud monitoring, the ecosystem reached a level of stability that encouraged those in the informal sector to finally abandon cash in favor of secure digital alternatives. The progress observed from 2026 into the following years demonstrated that while speed was the initial goal, reliability and affordability were the true catalysts for economic equity. Moving forward, the focus remained on strengthening the infrastructure to ensure that digital payments functioned as a universal public utility rather than a luxury service reserved for the urban elite.