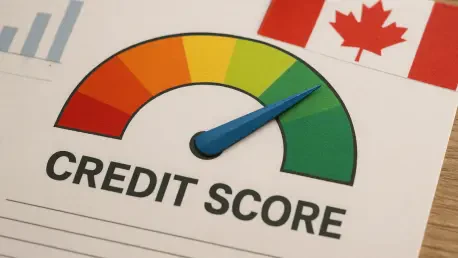
Recent survey data reveals that fifteen percent of Canadians have never checked their credit score while another five percent do not know how to access the information. This transparency gap often stems from a fundamental misunderstanding of how the national credit reporting system operates in 2026. Financial health is frequently viewed through the lens of income and savings, yet the three-digit number assigned by bureaus like Equifax and TransUnion carries immense weight in determining purchasing power. For many, the first encounter with a credit score occurs only when a major life event, such as applying for a mortgage in a competitive market, requires a deep dive into personal data. Understanding that a score typically ranges from 300 to 900 is the first step in demystifying the process. Within this framework, a score between 660 and 724 is generally categorized as good, while anything exceeding 760 is considered excellent. Lenders use these figures to predict the probability of default, making the score a vital metric for risk assessment.
The disparity between knowing one’s score and understanding its implications represents a significant hurdle for the average consumer. A lower score, particularly one falling into the low 600s, often results in higher interest rates or rejection from primary banking institutions. This financial friction can add thousands of dollars in extra costs over the lifespan of a loan, effectively penalizing those who have not yet optimized their credit profiles. However, the system is designed to be dynamic, reflecting current behaviors rather than serving as a permanent record of past mistakes. Experts emphasize that the score is essentially a snapshot of a consumer’s creditworthiness at a specific moment in time. By recognizing that the model evaluates factors such as payment history and account length, individuals can begin to navigate the system with greater confidence. This realization shifts the focus from anxiety to specific actions that influence the number, allowing for a proactive approach to personal financial management.
1. Establishing Reliability: The Impact of Timely Payments
Submitting payments on time stands as the single most influential factor in determining an individual’s credit score across all major Canadian reporting agencies. Every billing cycle provides an opportunity to demonstrate reliability to potential lenders, and even a single missed payment can trigger a noticeable decline in one’s rating. Financial institutions prioritize payment history because it serves as the most accurate predictor of future behavior. When a consumer consistently meets their obligations by the due date, it signals a low risk of delinquency, which encourages banks to offer more favorable terms. The impact of punctuality extends beyond credit cards to include utility bills and personal loans, all of which contribute to the holistic view of a borrower’s habits. Maintaining a pristine payment record is essential for anyone looking to transition from subprime to prime status. This foundational habit creates a ripple effect, strengthening the overall profile for lenders who demand high levels of responsibility.
To ensure that deadlines are never missed, many successful individuals leverage modern technological tools to manage their financial obligations. Setting up automated bank transfers or digital calendar reminders can eliminate the risk of human error or forgetfulness. However, the ability to make these payments consistently is deeply rooted in the practice of living within one’s financial means. Avoiding lifestyle creep, where expenses rise in tandem with income, is critical for maintaining the necessary cash flow to cover monthly bills. Financial discipline requires a level of honesty regarding one’s spending habits and a willingness to prioritize debt obligations over discretionary purchases. By aligning monthly expenditures with income, a consumer creates a sustainable environment where bill payments become a non-negotiable part of their routine. This structural approach to money management does more than just boost a credit score; it fosters a sense of financial literacy that empowers the individual to make better long-term decisions.
2. Managing Obligations: Minimum Payments and Budgetary Discipline
There are occasions when unexpected financial pressures make it difficult to settle a credit balance in full by the end of a billing cycle. In such scenarios, covering at least the lowest required amount is a vital strategy to prevent the account from falling into a state of delinquency. While paying the full balance is always the preferred method to avoid interest charges, making the minimum payment ensures that the account is reported as current to the credit bureaus. This small action protects the integrity of the payment history, which is the most significant component of the credit score calculation. If meeting even the minimum requirement becomes a challenge, it is imperative to contact the lender immediately. Most financial institutions are willing to negotiate temporary terms, such as extending the loan duration, to help a borrower avoid a formal default. Proactive communication demonstrates a commitment to debt repayment and can prevent long-term damage to a credit reputation.
Establishing a robust budget is another essential component in managing debt levels and ensuring that minimum payments are always feasible. By meticulously tracking every dollar that enters and exits a household, individuals can identify areas where spending can be curtailed to free up funds for debt service. This process involves a detailed analysis of fixed costs versus variable expenses, allowing for a clearer understanding of how money is allocated throughout the month. Developing a savings cushion can also provide a safety net that prevents the need to rely on high-interest credit during lean periods. When a consumer has a clear grasp of their financial landscape, they are better equipped to handle the fluctuations that often lead to missed payments. This strategic oversight reduces the psychological stress associated with debt and allows for a more methodical approach to repayment. Ultimately, the goal is to move beyond the minimum payment stage as quickly as possible.
3. Optimizing Utilization: Strategic Use of Available Credit Limits
Accepting pre-approved credit offers may seem counterintuitive to those trying to reduce debt, but it can be a highly effective tactic for improving a credit score. The key to this strategy lies in the concept of the credit utilization ratio, which measures the amount of revolving credit a person is using compared to their total available limit. When a lender increases a credit limit and the borrower maintains their current spending levels, the utilization ratio automatically drops. A lower ratio is viewed favorably by credit bureaus because it suggests that the individual is not overextended and possesses a healthy buffer of available funds. For instance, having a high limit but only using a small portion of it indicates to potential creditors that the consumer manages their credit responsibly and does not rely on borrowed funds for survival. This approach allows the score to climb steadily without requiring the individual to change their fundamental lifestyle or spending, provided they keep their balances low.
Financial experts generally recommend that consumers aim to keep their total credit utilization below thirty percent of their overall available limit. To illustrate this, an individual with a total credit limit of ten thousand dollars should strive to keep their combined balances below three thousand dollars. Surpassing this threshold can signal to lenders that a person is becoming overly dependent on credit, which may lead to a decrease in their score. By intentionally managing this ratio, a borrower can demonstrate a level of sophistication in their financial dealings that is highly prized by banks. Furthermore, keeping accounts open for long periods contributes to the length of credit history, which is another factor in the scoring process. The combination of high available limits and low usage creates a profile of stability and restraint. This strategy only works if the additional credit is treated as a safety margin rather than an invitation for increased consumption, which requires significant discipline.
4. Consolidating Debt: Improving Efficiency and Interest Rates
Merging outstanding debts into a single, more manageable product is a strategic move that can streamline the repayment process and reduce overall interest costs. Many Canadians find themselves juggling multiple high-interest obligations, such as various credit card balances, which can lead to monthly interest charges that eat away at the principal. By consolidating these debts into a personal line of credit or a structured consolidation loan with a lower interest rate, a borrower can ensure that more of their monthly payment goes toward reducing the actual debt. This transition simplifies the financial landscape by replacing multiple due dates and interest rates with a single, predictable monthly obligation. Beyond the immediate convenience, debt consolidation can also have a positive impact on the credit score by reducing the number of accounts with high utilization. The primary goal is to shift from expensive debt to a more affordable alternative, thereby accelerating the timeline for becoming debt-free.
The success of a debt consolidation strategy depends heavily on the borrower’s ability to resist the temptation of accumulating new balances on the original accounts. Once credit cards are paid off through a consolidation loan, it is vital to maintain those accounts with a zero balance or use them very sparingly. If an individual begins to spend on those cards again while still paying off the consolidation loan, they risk doubling their debt load and causing severe damage to their financial health. This scenario can lead to a rapid decline in credit scores and an unsustainable financial burden. To prevent this, some financial advisors recommend keeping the old accounts open to preserve the length of credit history but physically removing the cards from daily use. This approach ensures that the credit utilization ratio remains low while preventing the impulse to spend. Discipline and a clear focus on the long-term goal of financial freedom are the hallmarks of a successful and effective consolidation plan.
5. Assessing Long-Term Progress: The Path to Financial Stability
The process of rehabilitating a credit score in Canada requires a combination of strategic planning, behavioral adjustment, and consistent monitoring. Individuals who successfully navigated this journey discovered that the score was less a static judgment and more a reflection of their ongoing financial habits. By prioritizing punctual payments and managing credit utilization with precision, many were able to move from subprime categories into more favorable lending tiers. The shift toward a higher score opened up opportunities for better mortgage terms and lower interest rates on various consumer loans, which ultimately saved significant sums of money. Furthermore, the decision to consolidate high-interest debts into more efficient products proved to be a turning point for those seeking to regain control of their cash flow. It became clear that checking the score was merely the beginning of a larger commitment to fiscal transparency and literacy for every participant.
Moving forward, maintaining a healthy credit profile remained a cornerstone of financial stability, necessitating a proactive stance on budgeting and debt management to ensure that personal goals were consistently achieved. For those who had previously avoided looking at their data, the act of confronting the numbers served as a catalyst for meaningful change. It was observed that small, incremental steps, such as setting up automated reminders and reducing discretionary spending, led to substantial improvements over time. Seeking professional advice from a financial advisor also provided tailored solutions for complex situations, helping individuals navigate the intricacies of credit reporting with greater ease. The ultimate takeaway was that while the score served as a gateway to financial opportunities, it was the underlying discipline and informed decision-making that provided the true foundation for long-term prosperity. Continued vigilance and education were the tools used to sustain these hard-won financial gains.